All Categories
Featured
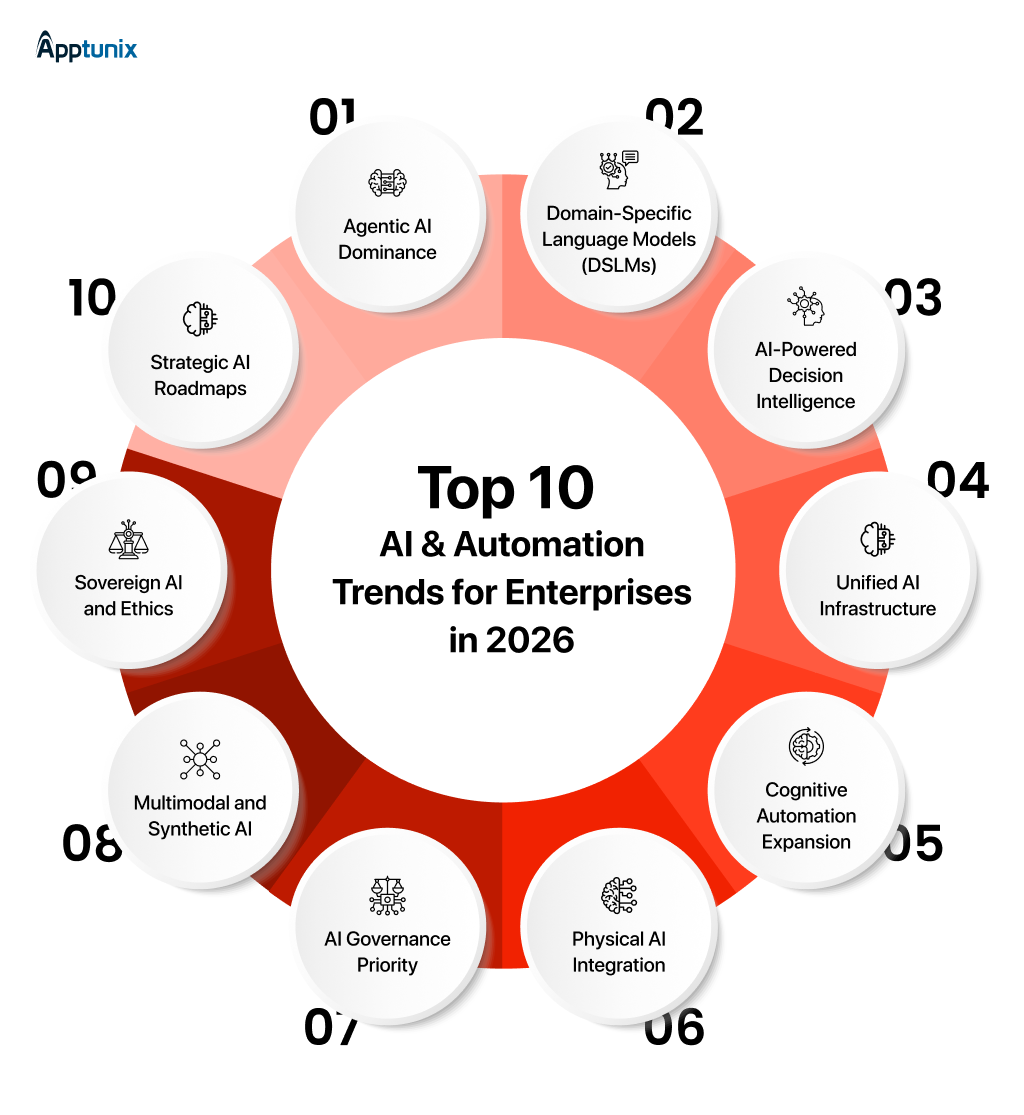

Building an Impactful AI Strategy for 2026
Table of Contents
Traditional fintech and e-commerce platforms like Tabby are now retrofitting AI-native layers onto their existing architectures. This upgrade cycle creates assessment advantages that compound gradually. The differentiation between "AI-native" and "AI-enabled" startups will end up being the primary filter for institutional financiers examining GCC opportunities in 2026. Fadi Ghandour's implicit review of the region's startup community brings analytical weight: the next unicorns should be built on AI automation, not market arbitrage.
AI-adjacent infrastructure companies brought in the largest rounds, while consumer-facing platforms without exclusive innovation components saw extended fundraising timelines and lower assessments.-- Secondary deals will become vital as venture funds method later stages and start-up appraisals increase.
The covert logic is counterproductive: secondary markets alter the "exit-only" state of mind that has controlled GCC startup culture. Founders can now sell partial stakes without activating an IPO, enabling them to maintain operational control while supplying liquidity to early financiers and staff members. This system creates a more mature capital environment where companies can stay personal longer while still gratifying early capital providers.
Are Middle Eastern Enterprises Ready for Advanced AI?Both jurisdictions need secondary liquidity facilities to bring in global family offices and institutional investors who require versatile exit mechanisms (Source 3: Market Structure Analysis). The development of devoted secondary trading platforms, or the integration of secondary abilities into existing exchanges, will be a specifying facilities story of 2026. For venture funds approaching their maturity horizons, secondary markets represent the difference in between returning capital to minimal partners on schedule versus looking for extensions.
-- International AI labs are establishing long-term operations in Abu Dhabi and Riyadh, drawn by two factors that the GCC has in abundance: capital and energy infrastructure. Large language design training requires both funds and industrial-scale computing power, making the Gulf's sovereign wealth funds and energy assets uniquely attractive to AI designers.
How GCC Tech Startups Lead 2026 Innovation
Unlike previous waves of Chinese tech expansion that focused on consumer hardware and e-commerce, the existing expansion targets AI infrastructure, cloud computing, and smart city agreements. Mid-tier Chinese AI companies, constrained by domestic competitors and worldwide sanctions, view the GCC as a neutral market where they can deploy innovation without geopolitical friction.
International AI companies establishing Gulf operations develop talent pipelines and knowledge transfer mechanisms that regional communities can not replicate naturally. They also combine the GCC's position as a third pole in the global AI landscape, unique from Silicon Valley and Beijing (Source 4: Geopolitical Analysis). For regional start-ups, this colonization presents both opportunities and dangers.
-- Saudi Arabia and the UAE's capital markets are engaged in direct competitors to become the region's favored exit route for technology companies. This competition, while advantageous for start-ups in the short-term, produces strategic complexity for companies preparing IPOs. Saudi Arabia's Capital Market Authority has carried out reforms designed to reduce listing timelines and disclosure requirements for technology companies.
How to Leverage AI for Greater Tech Results
IPO readiness has become a tactical concern in both jurisdictions. Unicorns Tabby, Tamara, and Salla are placed to check public markets in 2026, and their efficiency will set precedents for the whole environment. If these companies accomplish strong public market debuts, they will validate the GCC's capability to support large technology listings.
The competition reaches secondary listings and dual-listing structures. Business are significantly structuring their business entities to preserve optionality between Saudi and UAE exchanges, a versatility that adds legal and administrative intricacy however maximizes strategic alternatives.-- AI automation will disproportionately affect junior roles consisting of analysts, organizers, customer support, and fundamental coding functions.
Governments throughout the GCC accelerated adoption of AI as foundational facilities in 2025, acknowledging that automation is not optional but necessary for maintaining international competitiveness. This acceleration creates a tension between short-term employment goals and long-lasting efficiency imperatives.
Key Steps for Developing Digital FrameworksPhase three, noticeable on a 3-5 year horizon, will include essential restructuring of organizational hierarchies as AI decreases the need for middle management layers (Source 6: Labor Economics Analysis). Universities and schools in the GCC face existential pressure to transform their curricula. The standard model of understanding transmissionlectures, memorization, standardized testingis becoming outdated as AI systems can perform these functions more efficiently.
-- Big enterprises in the GCC are transitioning from AI experimentation to major deployment. This shift alters the need characteristics for innovation startups, which now discover themselves competing versus internal development groups at sovereign wealth funds, oil business, and government entities. The enterprise deployment wave produces a bifurcation in the start-up ecosystem.

Latest Posts
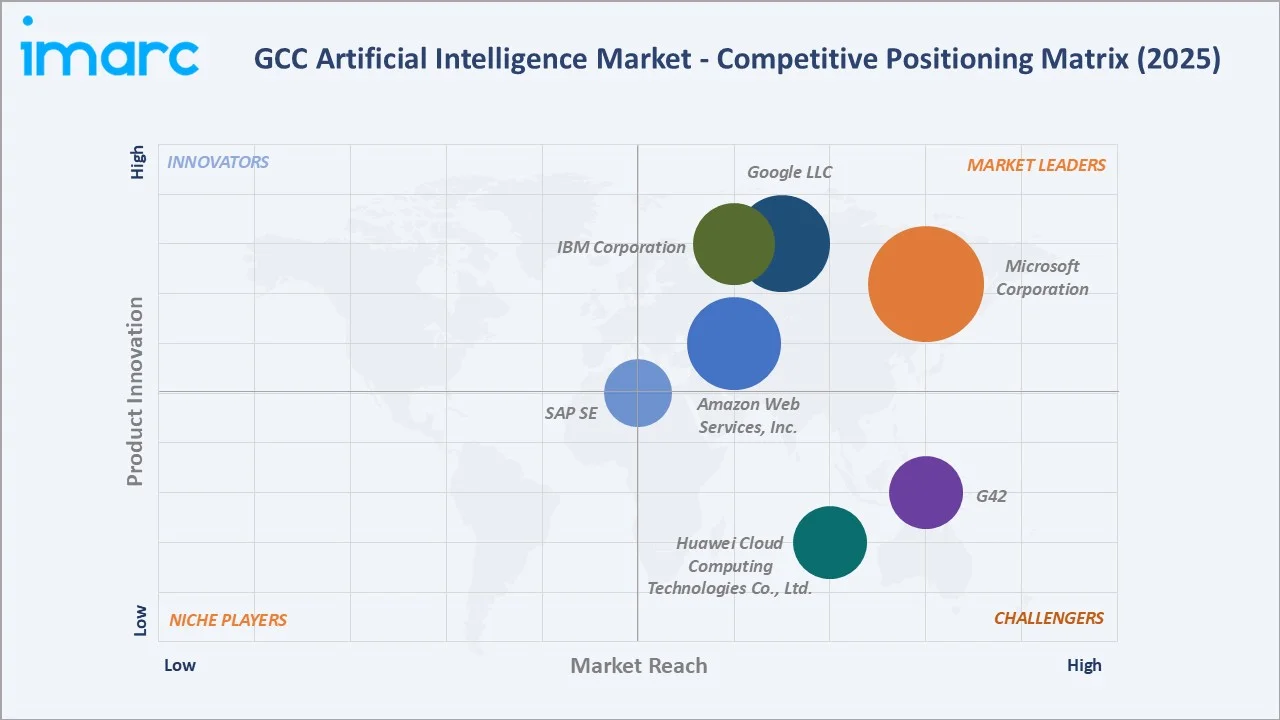
Why Advanced AI Is Crucial for 2026 Growth
Implementing Advanced AI to Scale Digital Roadmaps

The Role of AI in 2026 Market Growth